PAN INSIGHTAnalysis
AI Market Selloff: Trillion-Dollar Repricing and Circular Funding Risks
This analysis examines the AI market downturn where worldwide equities shed almost $9 trillion in value from August onward, per Reuters' November 20 report. It covers circular infrastructure funding dangers, market swings, and investor outlooks.
- Published
- Author
- Ярослав Малкин
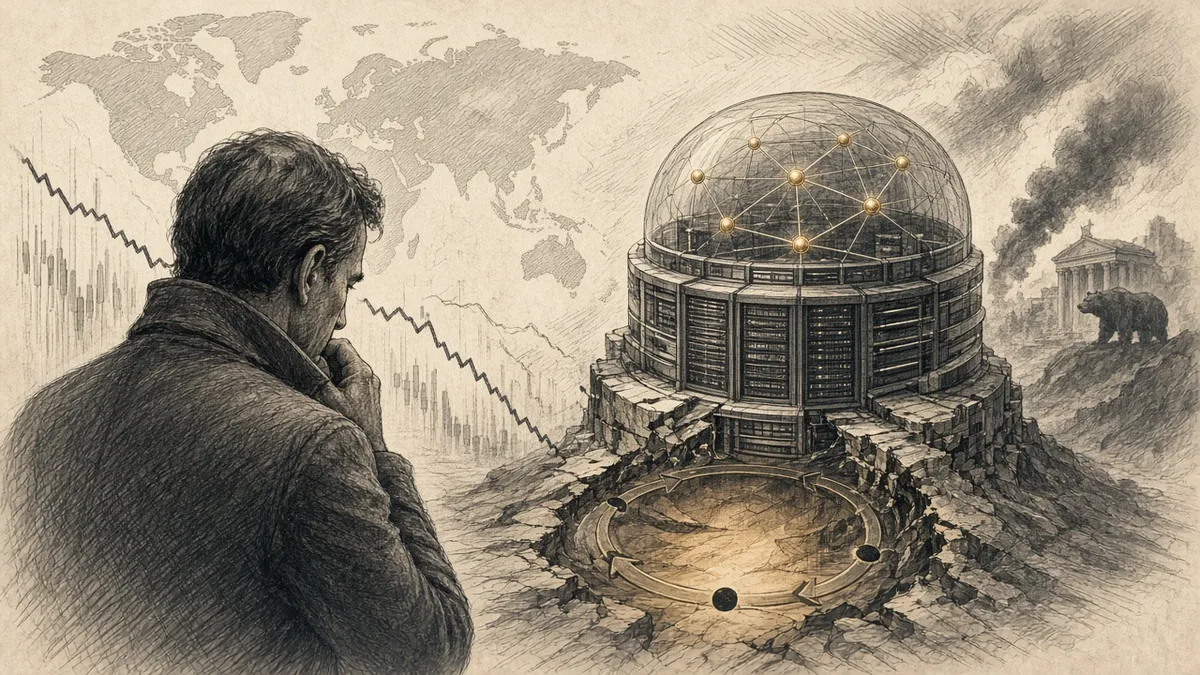
Investors began questioning exactly who would pay for artificial intelligence infrastructure and when spending would generate actual cash inflows. The technology shift may prove genuine even as its funding appears excessive. The current selloff forces recognition of both realities.
Reuters' November 20 review shows global equities have shed nearly $9 trillion in capitalization since August. On Friday the Nasdaq dropped 5.28%, the S&P 500 fell 3.70%, and U.S. chipmaker shares declined 10.7%. The VIX index rose to around 30. Ten-year Treasury yields eased to 4.948%.
Stock capitalization is not a bank deposit
Talk of vanished trillions sounds dramatic, yet it does not mean an equal amount of cash was destroyed. Market capitalization reflects the latest transaction prices, so repricing even a modest portion of shares alters the valuation of the entire float. Still, effects are felt: collateral values of portfolios drop, new share issuance grows harder, margin calls rise, and investors become less willing to fund risky assets.
Circular financing of AI projects
Large tech firms buy computing capacity, infrastructure suppliers expand output, investors price them on expected demand, and that demand partly hinges on continued funding across the ecosystem. A closed loop emerges in which one participant's anticipated spending becomes another's anticipated revenue. As long as end customers increase payments for AI-based products the arrangement can hold. If monetization lags, accumulated obligations begin weighing on balance sheets.
Reasons bond yields fall amid rate concerns
It seems contradictory at first: the market fears a firm Fed stance, yet Treasury yields decline. Investors are simultaneously weighing inflation, growth prospects, and demand for safe assets. When risk appetite collapses sharply, buying of government bonds can outweigh expectations of higher rates. For an analyst this is a key signal: lower yields do not always mean the central bank has eased policy.
Volatility speeds the selloff
A rising VIX alters the behavior of volatility-targeted strategies. Once portfolio risk exceeds the limit, managers cut positions regardless of long-term fundamentals. Margin requirements and options add further pressure. Declines can therefore accelerate without fresh negative news. An investor who reads every price bar as proof of technological collapse risks mistaking mechanical risk reduction for a change in economic potential.
Cryptocurrencies inside the mechanism
Bitcoin and other liquid digital assets may be sold simply to raise dollars even when headlines ignore blockchain. Institutional integration broadens the market while tightening its link to global risk. This does not refute the long-term scarcity thesis for bitcoin, yet it shows that short-term prices depend on capital availability. Watch ETF flows, leverage, stablecoin liquidity, and dollar funding markets.
Who captures the next growth phase
Within technology, preference may shift toward firms that already generate positive free cash flow, run high utilization on existing infrastructure, and deliver measurable returns on capital spending. Chipmakers depend not only on demand but also on inventory cycles and customer concentration. Power utilities and networks may benefit from data-center construction, but only if contracts deliver acceptable returns. Any investment thesis must rest on the economics of a specific business rather than broad faith in AI.
Scenarios
Base case 1–3 months: elevated volatility, selective recovery in quality assets; invalidation if credit spreads deteriorate sharply. Bullish case 3–12 months: earnings confirm AI monetization, capital spending stabilizes, demand returns; invalidation if free cash flow weakens. Bear case 1–9 months: investment cuts, credit-risk repricing, forced selling; invalidation if VIX and financial conditions normalize sustainably.
Conclusion
The takeaway is not that technological growth has ended. It is that markets are no longer willing to fund promises without compensation. For a long-term investor this may create opportunities, but only after rigorous balance-sheet and scenario checks. Optimism without discipline becomes an expensive mistake; discipline without openness to new technologies misses the next wave.
Method for testing an investment thesis
An investment conclusion must rest on the gap between an observed fact and the assumption that it will continue. Even an accurate macroeconomic figure carries no ready buy or sell signal: the price may already embed much of the expectation. Therefore compare the news with consensus, prior price action, and market positioning. It is equally important to check whether the change is a calendar, seasonal, or inventory effect or a genuine demand shift. Strong analysis begins not with a confident forecast but with the conditions under which the forecast would fail.
Particular attention should go to financing structure. A company with a strong product and high demand can still be vulnerable if it must refinance debt at an unfavorable moment. Conversely, a business with low leverage and ample liquidity can weather a temporary sales dip while retaining capacity to invest in the next cycle. Assessment requires comparing debt maturities, free cash flow, debt-service costs, and access to external capital. Market volatility often reveals differences between firms that looked equally robust during the rally.
Sources
The article was prepared by an analyst from the analytical department of tradepas.com: Yaroslav Malkin